










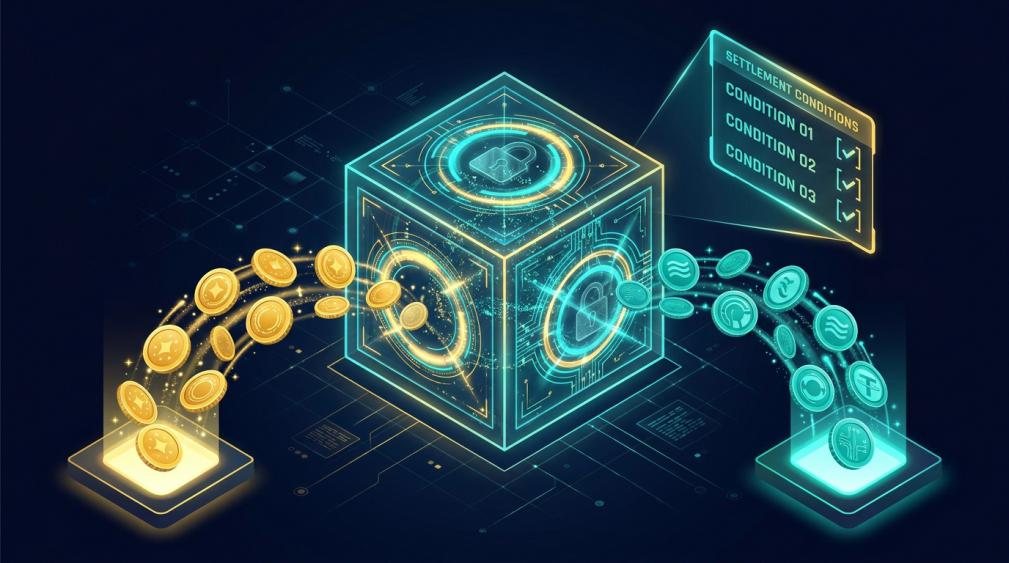
Smart contract escrow holds assets in code and releases them only when agreed conditions are met, such as both legs of a trade being funded, a delivery being confirmed by an oracle, or approvals from named parties. It can reduce counterparty risk and speed settlement, but it still needs legal terms, reliable data and a dispute process.
Key takeaways
- Escrow logic: deposit, verify conditions, release or refund, with deadlines.
- Conditions can be on-chain (both parties funded) or off-chain (documents, delivery), which require trusted data feeds or approvers.
- Code cannot settle every dispute: legal agreements and an arbiter remain essential.
- Main risks: contract bugs, oracle failure, key compromise of approvers and legal enforceability.
Traditional escrow relies on a trusted third party and manual checks. Smart contract escrow replaces parts of that with code that both sides can inspect. This guide explains how it works, a worked example, failure points and diligence questions. For simultaneous exchange without escrow, see atomic swaps and T+0 settlement.
How Smart Contract Escrow Works
- Agreement: parties sign legal terms that reference the escrow contract and its conditions.
- Deployment: contract is deployed (often from an audited template) with addresses, amounts, deadlines and approvers.
- Funding: one or both parties deposit tokens or stablecoins.
- Verification: contract checks conditions using on-chain data, oracles or signatures from approvers.
- Release or refund: assets move automatically when conditions are met, or return after a deadline.
- Dispute path: a named arbiter or multi-party vote can override in defined cases.
Types of Release Conditions
| Condition | Example | Trust needed |
| Both legs funded | Tokenized bond and stablecoin payment both deposited | None beyond the code |
| Time-based | Release after a lockup or refund after a deadline | None beyond the code |
| Multi-party approval | 2-of-3 approvals from buyer, seller and agent | Approvers’ key security |
| Oracle data | Shipment confirmed, price threshold, interest rate fixing | Oracle accuracy and availability |
| Document verification | Signed title transfer uploaded and hashed | Party verifying the document |
Worked Example: A Tokenized Real Estate Sale
Illustrative only. A fund sells tokens representing a $12 million property interest to a buyer.
| Step | Action | Escrow status |
| Day 0 | Buyer deposits $12M in stablecoins; seller deposits property tokens | Both legs locked |
| Day 3 | Title agent approves legal transfer documents | 1 of 2 approvals |
| Day 4 | Buyer’s counsel approves | 2 of 2: tokens to buyer, stablecoins to seller, simultaneously |
| Alternative | Approvals not received by Day 14 | Automatic refund to both parties |
Neither side is exposed to the other failing to deliver, and settlement takes days rather than weeks. The legal agreement still defines what happens if the title is later disputed.
Free educational tool
How well do you understand settlement risk?
The Readiness Quiz helps you check your understanding of settlement, custody and smart contract risks.
Educational tool. Results are not investment advice.
Where Smart Escrow Can Fail
| Risk | Example | Mitigation |
| Code bug | Funds stuck or released early | Audited templates; formal review; caps |
| Oracle failure | Wrong or missing data | Multiple sources; fallback approvers |
| Approver key compromise | Attacker approves release | Multi-sig approvers; hardware keys |
| Legal mismatch | Code outcome differs from contract terms | Legal terms specify which prevails |
| Stablecoin risk | Payment asset frozen or depegged | Approved, regulated payment stablecoins |
| Upgradeability | Admin can change contract | Disclosed admin rights; time delays |
For audit practices, see smart contract security audits.
Diligence Checklist
- Is the escrow contract audited, and is the deployed code the audited version?
- Who can upgrade or pause the contract?
- Which conditions rely on oracles or human approvers, and how are they secured?
- What happens at the deadline if conditions are not met?
- Does the legal agreement reference the contract and define dispute resolution?
- Which payment asset is used, and is it acceptable to both parties’ compliance teams?
Work With Kenson Investments
Kenson Investments’ digital asset specialists focus on education around settlement and smart contract risk. Explore our digital asset consultation services or contact the team to learn more.
Disclaimer: The information provided on this page is for educational and informational purposes only and should not be construed as financial advice. Digital assets involve significant risk, including the possible loss of principal, and past performance is not indicative of future results. Always conduct thorough research and consult a qualified financial advisor before making investment decisions.
Digital asset regulation in the United States is still developing. Some areas, such as payment stablecoins, now have a federal framework, but comprehensive market-structure legislation has not yet been enacted. None of the information provided by Kenson LLC should be considered financial investment advice. Please consult your Registered Financial Advisor for guidance. Kenson LLC does not offer any products regulated by the SEC, including equities, registered securities, ETFs, stocks, bonds, or equivalents.
References
- GeeksforGeeks — What is an escrow smart contract?



