










Digital Assets in Everyday Transactions: What Actually Works in 2026
Digital assets in everyday transactions are usable in 2026, but not in the same way everywhere. A shopper may pay with a supported stablecoin at an online checkout; another may spend through a card service that first converts cryptocurrency; a freelancer may receive a digital-dollar payout. Behind an ordinary card purchase, banks may also settle using blockchain rails without the customer ever holding a token. Those are four different payment arrangements with different costs, protections and eligibility rules.
The practical test is whether someone can complete a purchase, receive a refund, access spendable funds and resolve an error under published terms. A transfer that confirms on-chain is not, by itself, proof that a merchant received usable money. Availability described below reflects provider documentation reviewed October 21, 2026; geographic coverage and product features can change.
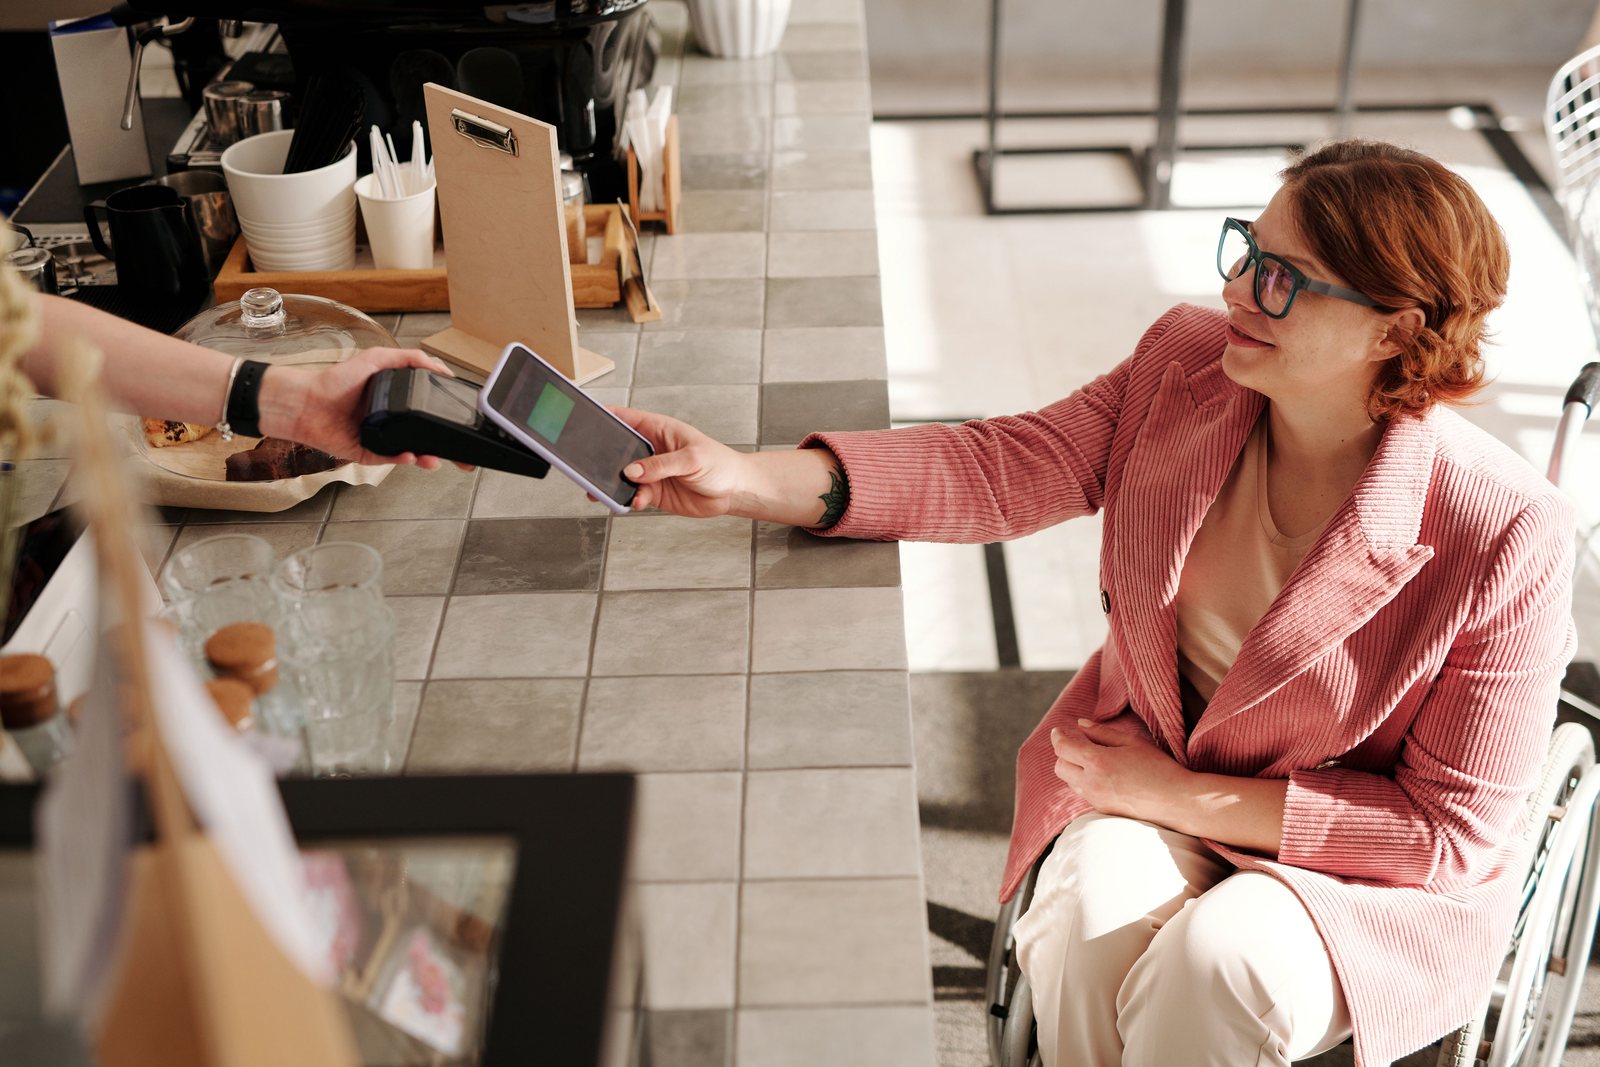
Online retail is the clearest consumer-facing example. Shopify documents USDC checkout through Shopify Payments, subject to store eligibility, supported networks, onboarding and payment-method activation. Its current guidance names selected regions in North America, Europe and Asia-Pacific, not universal availability. Merchants can receive proceeds in a supported payout currency or, where available, claim USDC. The checkout runs within an existing e-commerce workflow rather than asking every merchant to manage blockchain infrastructure from scratch.
Other uses include a freelancer receiving a stablecoin transfer, an international supplier accepting an agreed digital-dollar settlement asset, and a cardholder spending digital assets through a provider that converts them. These are workable models only where the payer, intermediary and recipient have access to compatible services. They should not be confused with blanket acceptance at neighborhood stores or the ability to spend any token in any country.
A stablecoin aims to track a reference currency, but that does not make it a bank deposit or guarantee redemption by any holder. Redemption eligibility, issuer reserves, the intermediary and the secondary-market price remain important. Kenson’s guide to stablecoin structures and risks addresses these characteristics in greater depth; the emphasis here is what they mean at checkout.
Free educational tool
Are you ready for digital assets?
Seven quick questions on knowledge, mindset and goals, with one honest answer about where you stand.
Educational tool. Results are not investment advice.
Four Payment Models, Four Different Customer Experiences
The word “crypto payment” can conceal very different workflows. Identifying the route is the first step in evaluating costs, recourse and settlement time.
| Payment model | What actually happens | Practical limitation |
|---|---|---|
| Direct stablecoin checkout | Customer sends a supported token through an enabled merchant payment service | Limited regions, wallets, tokens and refund features |
| Crypto-funded card | Provider converts or uses digital assets to fund an ordinary card purchase | Conversion fees, provider terms and asset availability |
| Stablecoin transfer or payout | Sender transfers a supported token to a recipient wallet or payout provider | Off-ramp eligibility, network choice and local cash access |
| Institutional stablecoin settlement | Banks or processors settle obligations using tokens behind a conventional card experience | Not equivalent to consumers paying merchants in cryptocurrency |
In direct wallet checkout, the merchant or payment processor specifies an asset, blockchain network and receiving arrangement. A customer must hold the correct token on the correct supported network. A mistaken network, incompatible wallet or address error can leave a payment delayed or unrecoverable. The merchant may be protected from having to custody tokens if its processor converts and pays out local currency, but that introduces a service-provider dependency.
A crypto-funded card looks familiar because a merchant sees an ordinary card transaction. The card program may liquidate crypto at the time of purchase or draw on an already funded balance. The user must examine the rate, spread, card charges and whether the provider can suspend conversion. Conventional card features cannot be assumed unless the specific agreement provides them.
Direct wallet payouts can be useful where a recipient accepts and can use a stablecoin. However, recipient access to a bank account, required checks, local currency conversion and tax reporting often determine whether the payment has actually solved the original problem. A blockchain timestamp measures one leg, not the entire experience. Kenson’s explanation of settlement speed and finality covers that underlying technical distinction.
What Current Shopify and Visa Examples Actually Demonstrate
Shopify supplies a documented merchant-checkout example, rather than a hypothetical claim about widespread adoption. Its support rules specify compatible USDC networks and require eligible Shopify Payments accounts. The guidance also says USDC cannot be used for subscription purchases through that method, partial capture is unavailable, and shoppers cannot open order disputes through the USDC method. Merchants remain responsible for their own returns and customer-service processes. These restrictions matter more to a buyer than the theoretical number of transactions a blockchain can process.
Visa represents a separate development. On December 16, 2025, Visa announced USDC settlement for participating U.S. issuer and acquirer partners, initially identifying Cross River Bank and Lead Bank. Visa stated that this arrangement did not require any change to the consumer card experience. It demonstrates a potential change in how financial institutions discharge obligations, not proof that every Visa customer can pay with a stablecoin or receive USDC refunds.
Even where stablecoin liquidity infrastructure operates seven days a week, merchant disbursement may still depend on provider payout schedules, banking availability and verification requirements. Businesses comparing products should measure when the beneficiary can actually spend or withdraw funds, rather than treating near-instant network confirmation as the complete settlement time.
The True Cost of a $100 Digital Asset Purchase
A blockchain transaction fee is only one component of payment cost. Depending on the route, there may also be an acquisition spread, exchange commission, payment-processor fee, conversion or off-ramp charge, network gas fee and bank payout cost. The payer and merchant may bear different portions, so a claim of “low fees” is incomplete without saying whose fees are being counted.
Free educational tool
Test a hypothetical allocation against history
Choose assets and weights, set contributions and costs, and review historical outcomes, volatility and drawdowns. Historical data, not a forecast.
Educational tool. Results are not investment advice.
Consider a hypothetical direct stablecoin transfer for a $100 purchase. The customer acquires 100 units of a dollar-referenced stablecoin at a 0.8% acquisition cost, paying $100.80, and separately pays a network fee equivalent to $0.10. The merchant receives 100 tokens, incurs a 0.5% conversion charge ($0.50), and pays a $0.50 withdrawal fee. The merchant obtains $99.00, while the customer has spent $100.90. The combined payment-related friction is $1.90, split between the two parties.
| Illustrative step | Customer | Merchant |
|---|---|---|
| Acquire 100 stablecoins | Pays $100.80 | Not applicable |
| Transfer fee | Pays $0.10 | Receives 100 tokens |
| Convert and withdraw | No additional assumed charge | Pays $0.50 + $0.50 |
| Final result | Total outlay: $100.90 | Usable proceeds: $99.00 |
These are invented teaching assumptions, not Shopify fees, market averages, or a live quote. They exclude taxes, failed transfers, exchange-rate movements and customer-service costs. The case also assumes the transfer fee is paid separately and that 100 tokens arrive in full. A managed checkout with a different fee structure, including a gas-sponsored checkout, would require its own calculation.
Compare like with like. Measure the total amount the customer gives up, the net sum the merchant receives, the time until that sum is usable, and who handles exceptions. Under different assumptions a digital asset route could be cheaper or more expensive than an established payment service. The calculation should determine the conclusion, not the payment technology used.
Refunds, Consumer Rights, Regulation and Tax Obligations
A successful blockchain payment does not automatically include the chargeback process familiar from many card transactions. In a direct wallet transfer, an irreversible instruction may need a separate refund transaction initiated by the merchant or platform. Returns policies, mistaken payments, fraud remedies and consumer-law protections depend on the payment contract and jurisdiction. A buyer should read the refund route before paying, especially when the payment asset can change value or the original wallet is no longer accessible.
Stablecoin backing and direct redemption should also be checked separately. A shopper holding USDC through a third-party wallet may be able to spend it on a supported checkout without being eligible to redeem directly with the issuer. In practice, access to fiat currency may depend on an exchange, payments provider or eligible institutional account. Price stability targets do not remove intermediary or liquidity risks, and stablecoins generally do not confer ordinary deposit-insurance protection simply by being dollar-referenced.
U.S. regulation moved beyond proposals in 2025. The GENIUS Act, enacted July 18, 2025, establishes a federal framework for payment stablecoins. Under its statutory effective-date provision, the Act takes effect on the earlier of January 18, 2027, or 120 days after primary federal payment stablecoin regulators issue qualifying final implementing regulations. As reviewed October 21, 2026, the broader statutory start should not be described as already fully effective. Other applicable laws and supervisory requirements can still matter in the meantime.
The European Union also applies the Markets in Crypto-Assets Regulation (MiCA) to relevant crypto-asset issuers and service providers. Its requirements are different from U.S. rules, and the authorization of one provider does not establish consumer access to every payment method. Cross-border availability depends on jurisdiction, provider licensing and individual product terms. Avoid inferring worldwide approval from a global promotional announcement.
Tax treatment is another practical obstacle. The Internal Revenue Service states that using digital assets to buy goods or services is a disposition for U.S. federal tax reporting purposes. A consumer can trigger reportable activity even for a small purchase, although whether a gain or loss arises depends on the asset’s value and cost basis. People receiving payment for services may have income-reporting obligations. Tax rules differ by jurisdiction; payment records should preserve dates, amounts, exchange rates, fees and transaction identifiers.
Free educational tool
What is your crypto risk profile?
Five quick questions about your mindset, time horizon and behaviour, with a reading list matched to your profile.
Educational tool. Results are not investment advice.
A Pre-Payment Check for Consumers and Merchants
Before paying, confirm the merchant supports the specific asset and network, the displayed exchange rate, who pays gas or conversion fees, and the currency in which the merchant will receive proceeds. Verify the address or integrated checkout rather than following an unsolicited payment instruction. For cross-border transfers, check recipient eligibility, cash-out channels, withdrawal limits, and expected time to usable funds.
Before accepting payments, merchants should verify processor licensing and eligibility, settlement choices, reserves or issuer disclosures where relevant, refunds, failed-payment procedures, record retention and accounting treatment. They should also decide who is accountable when a transfer is confirmed on-chain but no corresponding order or payout is recorded. Digital asset operational risk includes operational exceptions that are invisible in a wallet balance.
A useful record of the transaction includes the order number, asset and network, amount tendered, fees, wallet or processor reference, transaction hash where available, fiat value at payment, and the final payout or refund status. The same evidence supports digital asset risk management, customer queries and accurate accounting. For business-system integration beyond the customer experience, Kenson’s enterprise blockchain implementation guide examines the architectural questions.
What Everyday Payment Adoption Really Means
In 2026, an ordinary purchase can involve digital assets, but that does not make every transfer a retail payment or every stablecoin a consumer-ready substitute for bank money. The decisive evidence is supported checkout access, full cost, dependable merchant receipt, realistic refund arrangements and legally appropriate service provision. Kenson Investments publishes educational research on the structures and risks behind digital asset markets. To ask about its research and educational resources, contact Kenson Investments.
Disclaimer: The information provided by Kenson Investments is for educational and informational purposes only and does not constitute financial, investment, legal, or tax advice, or a recommendation to buy, sell, or hold any digital asset. Digital assets involve significant risks, including market volatility, liquidity constraints, custody vulnerabilities, technological failures, counterparty exposure, and regulatory uncertainty. Their legal and regulatory treatment varies by asset, transaction, and jurisdiction. Past performance does not guarantee future results, and investors may lose some or all of their invested capital. Readers should conduct independent research and consult appropriately qualified financial, legal, or tax professionals before making investment decisions.



