










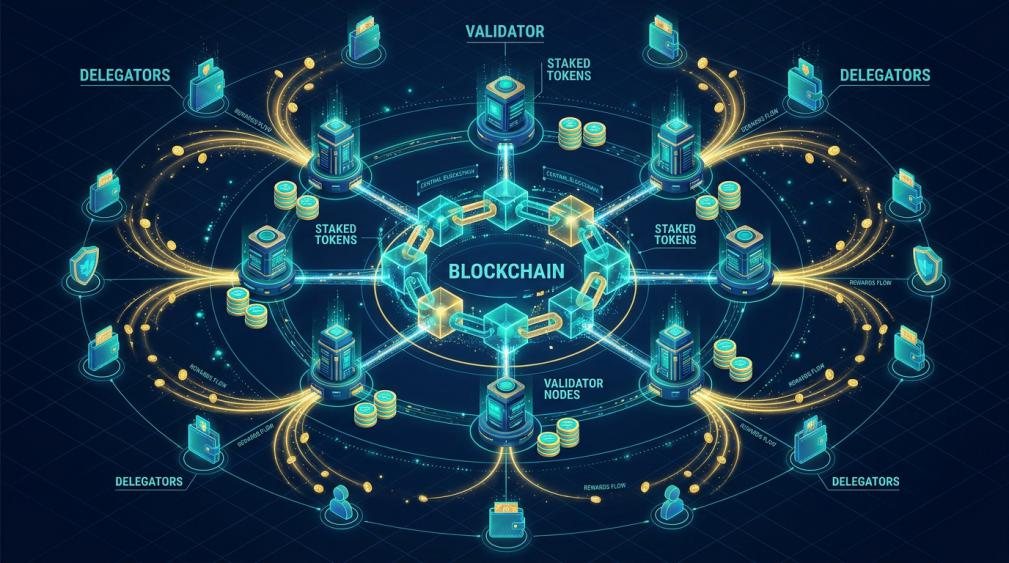
Proof-of-stake blockchains select validators based on tokens staked rather than computing power. Designs differ in who validates and how holders delegate: standard PoS, delegated PoS, nominated PoS and staked-authority models. Rewards come from new token issuance and transaction fees, so the real return depends on inflation and price, not just the headline rate.
Key takeaways
- Rewards come from issuance (new tokens) and fees, tips and MEV.
- High headline rates often come with high inflation; real yield can be much lower.
- About a third of all ETH was staked in 2026, earning around 2.6% a year.
- Mechanisms differ in decentralization, lockups and slashing rules.
This guide explains how the main staking designs work, where rewards come from, how to think about real yield, and the risks. For a beginner’s how-to, see staking for rewards; for institutional pools, see institutional staking pools.
Main Staking Designs
| Design | How validators are chosen | Examples | Trade-offs |
| Proof of stake (PoS) | Anyone meeting a minimum stake can validate; others delegate or use pools | Ethereum | Large validator set; higher minimums for solo validators |
| Delegated PoS (DPoS) | Holders vote for a limited set of block producers | EOS, TRON | Fast; fewer validators, more concentration |
| Nominated PoS (NPoS) | Nominators back validators; stake spread by algorithm | Polkadot | Fairer distribution; nominators share slashing |
| Delegated with bonding | Delegators bond to validators with unbonding periods | Cosmos chains | Liquid choice of validator; multi-week unbonding |
| Proof of Staked Authority (PoSA) | Small set of approved, staked validators | BNB Chain | High throughput; more centralized |
Where Rewards Come From
| Source | Description | Sustainability |
| Issuance | New tokens created by the protocol | Dilutes non-stakers; may fall over time |
| Transaction fees and tips | Paid by users | Depends on network demand |
| MEV | Value from ordering transactions | Variable; concentrated |
| Restaking / extra services | Additional rewards for securing other services | Extra risk layered on |
Nominal vs. Real Staking Yield
Real staking yield is the reward rate adjusted for token inflation. If a network pays 7% while supply grows 5%, stakers’ share grows only about 2% in real terms; holders who do not stake are diluted. Fee-funded rewards are more sustainable than issuance-funded ones.
Illustrative only.
| Network (hypothetical) | Nominal reward | Supply inflation | Approx. real yield |
| A | 7.0% | 5.0% | ~1.9% |
| B | 3.0% | 0.5% | ~2.5% |
| C | 12.0% | 11.0% | ~0.9% |
Network C’s headline rate is highest, but its real yield is lowest.
Free educational tool
Does staking risk fit your profile?
The Crypto Risk Profile Quiz helps you think through your tolerance for volatility, lockups and protocol risk.
Take the Crypto Risk Profile Quiz →
Educational tool. Results are not investment advice.
Slashing, Lockups and Other Risks
- Slashing: validators that double-sign or misbehave lose part of their stake; delegators may share the loss on some networks.
- Inactivity penalties: offline validators lose rewards.
- Unbonding periods: from days to several weeks, during which tokens cannot be sold.
- Concentration: large staking providers can control significant stake.
- Regulation: the SEC staff has said certain protocol staking activities are not securities offerings (SEC), but rules differ by country and product.
Questions Before Staking
- Where do the rewards come from: issuance or fees?
- What is supply inflation, and what is the real yield?
- How long is the unbonding period?
- What are the slashing rules, and do delegators share losses?
- How concentrated is stake among validators?
- What are the tax rules for staking rewards where I live?
Work With Kenson Investments
Kenson Investments’ digital asset specialists focus on education around proof-of-stake networks and staking. Explore our Ethereum resources or contact the team to learn more.
Disclaimer: The information provided on this page is for educational and informational purposes only and should not be construed as financial advice. Digital assets involve significant risk, including the possible loss of principal, and past performance is not indicative of future results. Always conduct thorough research and consult a qualified financial advisor before making investment decisions.
Digital asset regulation in the United States is still developing. Some areas, such as payment stablecoins, now have a federal framework, but comprehensive market-structure legislation has not yet been enacted. None of the information provided by Kenson LLC should be considered financial investment advice. Please consult your Registered Financial Advisor for guidance. Kenson LLC does not offer any products regulated by the SEC, including equities, registered securities, ETFs, stocks, bonds, or equivalents.
References
- SEC — Statement on protocol staking activities
- Ethereum staking data — Staking statistics
- Ethereum.org — Proof-of-stake



