










Proof of Stake vs. Proof of Work: How Consensus Shapes Staking Returns
Proof of work secures a blockchain by making miners spend computing power and electricity to add blocks. Proof of stake secures it by requiring validators to lock up the network’s own tokens as collateral, which can be partly destroyed if they act dishonestly. Staking rewards pay validators for that work.
Key takeaways
Proof of stake replaces energy cost with capital at risk, which is why it can pay a yield to holders.
On Ethereum, roughly 34% of ETH was staked by mid-2026, with consensus yields around 2.6% a year.
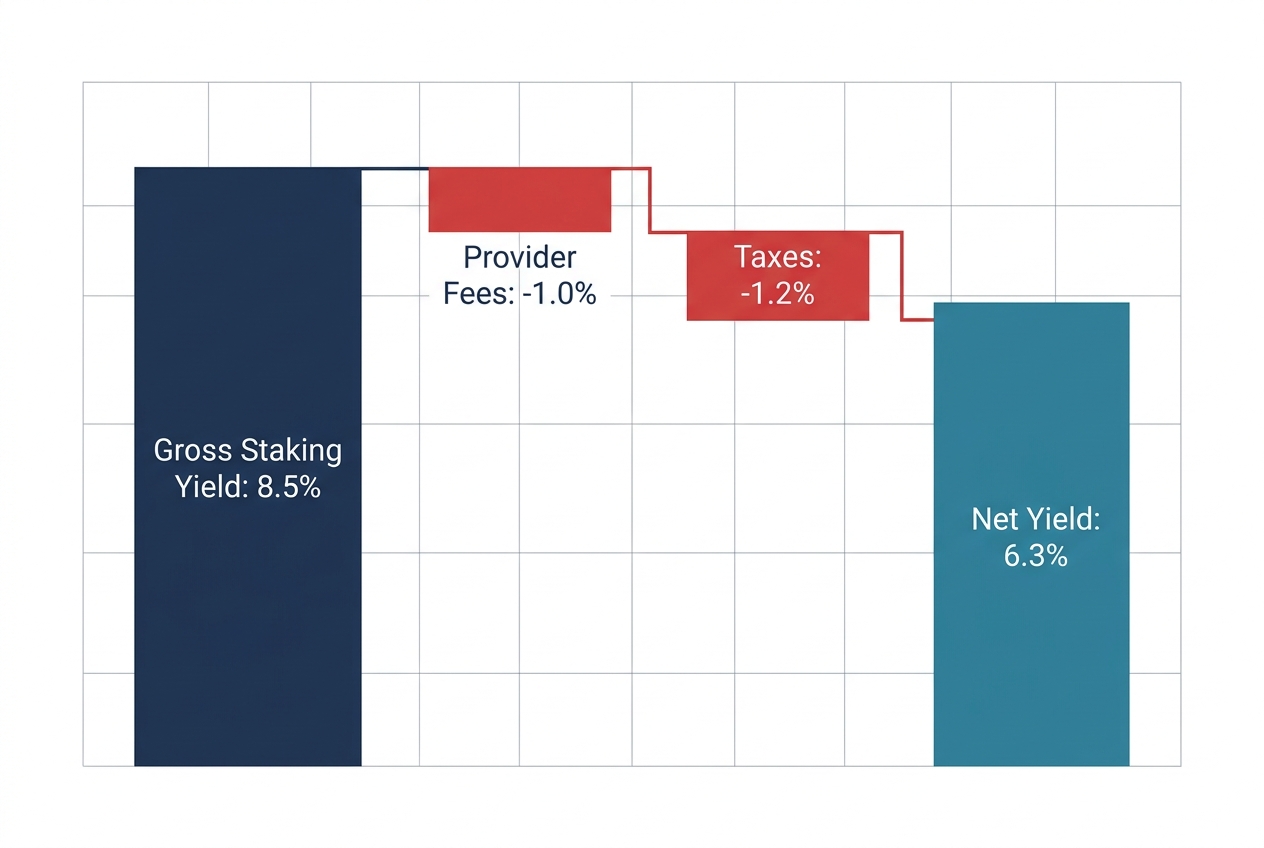
Headline staking rates are gross. Net return depends on provider fees, taxes, lockups, slashing risk and, above all, the token’s price.
US regulators have signalled that protocol and liquid staking are generally not securities transactions, but tax still applies.
Consensus mechanisms sound technical, but they matter to investors because they determine where a network’s security budget comes from and whether holders can earn a protocol-level reward. This guide covers the mechanics briefly, then focuses on what drives staking returns and what erodes them. For the practical and compliance steps of participating, see our compliance-aware guide to staking protocols.
How Proof of Work Secures a Network
In proof of work, miners compete to solve a computational puzzle. The winner adds the next block and earns newly issued coins plus transaction fees. Attacking the network would require controlling most of the computing power, which is extremely expensive on large networks.
Bitcoin is the best-known proof-of-work network. Its security comes from external, real-world cost: hardware and electricity. That makes it robust but energy-intensive, and it means ordinary holders do not earn a protocol reward simply for holding. Our guide to why investors consider Bitcoin covers that asset in more depth.
How Proof of Stake Works
In proof of stake, validators lock tokens as a bond. The protocol selects validators to propose and attest to blocks. Honest work earns rewards; provable misbehaviour, such as signing two conflicting blocks, triggers slashing, where part of the bond is destroyed.
Ethereum moved from proof of work to proof of stake in September 2022 (“the Merge”), cutting the network’s energy use by an estimated 99.9%+ according to the Ethereum Foundation. Later upgrades raised the maximum effective balance per validator from 32 ETH to 2,048 ETH, making it easier for large holders to consolidate validators.
| Factor | Proof of work | Proof of stake |
| Security resource | Computing power and electricity | Staked tokens (capital at risk) |
| Who earns rewards | Miners | Validators and delegators |
| Penalty for attacks | Wasted hardware and energy cost | Slashing of staked tokens |
| Energy use | High | Low |
| Main centralisation pressure | Cheap energy and hardware scale | Large staking providers and exchanges |
| Example networks | Bitcoin | Ethereum, Solana, Cardano |
Where Staking Rewards Actually Come From
Staking rewards come from two sources: new token issuance created by the protocol, and fees paid by users, including priority fees and MEV. Issuance is effectively a transfer from non-stakers to stakers, so only the fee portion is economic income generated by network usage.
This distinction matters. If a network issues 3% new tokens a year and pays that to stakers, a staker’s share of the network stays roughly constant while non-stakers are diluted. The “yield” protects against dilution more than it creates new value. Fee and MEV revenue, by contrast, depends on how much people actually use the network.
Issuance rewards: set by protocol rules; on Ethereum they fall as more ETH is staked.
Priority fees and MEV: vary with network demand and market volatility.
Staking ratio: more stake means each validator’s share of rewards shrinks. Roughly 34% of ETH was staked in mid-2026, up from about 29% at the start of that year (The Block).
Protocol changes: proposals can change reward curves. A mid-2026 Ethereum proposal (EIP-8361) would burn a rising share of rewards as the staking ratio grows; modelling cited by The Block suggested consensus yield could fall from about 2.6% toward 1.2% if adopted.
What Reduces Net Staking Returns
Net staking return equals gross rewards minus provider fees, taxes, and the opportunity cost of locked capital, adjusted for slashing and downtime risk. Token price changes usually outweigh all of these, so a positive staking rate can still produce a loss.
| Cost or risk | How it works | Typical effect |
| Provider commission | Exchanges and staking services keep a share of rewards | Often 5–25% of rewards |
| Lockups and exit queues | Unstaking can take days; on Ethereum, exit queues have at times stretched to several weeks | Cannot sell quickly in a downturn |
| Slashing | Bond partially destroyed for double-signing or similar faults | Rare but can be material |
| Downtime penalties | Offline validators miss rewards and pay small penalties | Usually minor |
| Liquid staking token (LST) risk | Receipt token may trade below the underlying asset in stress; adds smart contract risk | Liquidity at a discount |
| Taxes | In the US, rewards are generally income when received (IRS Rev. Rul. 2023-14) | Reduces after-tax yield |
| Price volatility | Rewards are paid in the token | Dominates total return |
Worked Scenario: Headline Yield vs. Net Result
Illustrative only. Assume an investor stakes 10 ETH worth $3,000 each ($30,000) through a provider for one year.
| Step | Calculation | Result |
| Gross rewards (assumed 2.8% incl. fees/MEV) | 10 ETH × 2.8% | 0.28 ETH |
| Provider commission (10%) | 0.28 × 10% | −0.028 ETH |
| Net rewards | 0.252 ETH (2.52%) | |
| Income value at receipt | 0.252 × $3,000 | $756 |
| Tax at an assumed 24% rate | $756 × 24% | −$181 (paid in cash) |
| After-tax reward yield | ($756 − $181) ÷ $30,000 | ~1.9% |
| If ETH ends the year flat at $3,000 | 10.252 ETH × $3,000 − $181 tax | $30,575 (+1.9%) |
| If ETH falls 20% to $2,400 | 10.252 ETH × $2,400 − $181 tax | $24,424 (−18.6%) |
The scenario shows why “2.6% yield” is the least important number in the decision. Staking can modestly improve the outcome of holding a token an investor already intends to hold. It does not offset meaningful price declines.
Free educational tool
See how price moves compare to staking rewards
Model bullish, bearish and flat scenarios for a digital asset allocation and see how much a reward rate matters relative to price changes.
Educational tool. Results are not investment advice.
Regulatory and Tax Context
US regulators have moved toward treating protocol staking as a technical service rather than an investment contract. SEC staff statements in 2025 and a March 2026 SEC–CFTC joint interpretation support that view. Staking rewards remain taxable, and rules differ by country.
May 2025: SEC staff stated that protocol staking on proof-of-stake networks generally does not involve the offer and sale of securities (Fenwick summary).
August 2025: SEC staff extended a similar view to certain liquid staking arrangements and receipt tokens (SEC).
March 2026: an SEC–CFTC joint interpretation described staking, including liquid staking, as administrative or ministerial activity (Baker Donelson summary). It is an agency statement of position, not legislation.
Tax: the IRS treats staking rewards as income once the taxpayer gains control of them; other jurisdictions vary. Staking through a custodian may also change who controls the assets.
Staking Due-Diligence Checklist
Is the reward mainly issuance (dilution protection) or fee revenue (usage-driven)?
What commission does the provider charge, and is it disclosed clearly?
How long does unstaking take, and what happens in a congested exit queue?
Who bears slashing losses: the investor or the provider?
If using a liquid staking token, how deep is its market, and how has it traded in past stress?
Who holds the keys, and what happens if the provider fails?
How will rewards be taxed and reported?
Frequently Asked Questions
Is staking yield guaranteed?
No. Reward rates change with network activity, the staking ratio and protocol upgrades, and rewards are paid in a volatile token.
Is proof of stake less secure than proof of work?
They secure networks differently. Proof of work relies on external energy cost; proof of stake relies on capital at risk. Each has different attack and centralisation trade-offs.
Can I lose staked tokens?
Yes, through slashing, provider failure, smart contract exploits in liquid staking, or simply a fall in the token’s price.
What is liquid staking?
A service that stakes tokens on the holder’s behalf and issues a tradable receipt token, allowing liquidity while staked at the cost of added smart contract and pricing risk.
Work With Kenson Investments
Kenson Investments’ digital asset specialists focus on education around staking, custody and risk. Explore our DeFi consultation services or contact the team to learn more.
Disclaimer: The information provided on this page is for educational and informational purposes only and should not be construed as financial advice. Digital assets involve significant risk, including the possible loss of principal, and past performance is not indicative of future results. Always conduct thorough research and consult a qualified financial advisor before making investment decisions.
Digital asset regulation in the United States is still developing. Some areas, such as payment stablecoins, now have a federal framework, but comprehensive market-structure legislation has not yet been enacted. None of the information provided by Kenson LLC should be considered financial investment advice. Please consult your Registered Financial Advisor for guidance. Kenson LLC does not offer any products regulated by the SEC, including equities, registered securities, ETFs, stocks, bonds, or equivalents.



